GST Due Dates NZ 2026/27: Complete Filing Calendar for Every Business
Most GST returns and payments are due on the 28th of the month after your taxable period ends. There are two standing exceptions: the period ending 30 November is due 15 January and the period ending 31 March is due 7 May. The exact due date also depends on how often you file your GST return. Full dates by filing frequency are below.
Already know your due date and just need the number? Use our free GST Calculator to add or remove 15% GST and build a multi-item invoice in seconds.
Table of Contents
General GST Due Date Rule
Answer block: Under section 16 of the Goods and Services Tax Act 1985, a GST return and its payment are due by the 28th of the month after your taxable period ends. Two exceptions exist specifically to avoid clashing with the Christmas/New Year closure period and with terminal tax deadlines:
| Period ending | Standard 28th rule would give | Actual due date | Reason for exception |
| 30 November | 28 December | 15 January | Avoids the Christmas/New Year office closure period |
| 31 March | 28 April | 7 May | Aligns with terminal tax due dates |
When the 28th or an exception date falls on a weekend or public holiday the due date automatically moves to the next working day. Confirm your own exact due date any time in myIR.
Two Monthly GST Due Dates 2026/27
Two monthly is the default GST filing frequency for most New Zealand businesses. Which cycle applies to you depends on your GST registration date and balance date.
Cycle A — periods ending on odd months (May, July, September, November, January, March):
| Taxable period | Period ends | Return & payment due |
| April–May 2026 | 31 May 2026 | 29 June 2026 (28 June falls on a Sunday) |
| June–July 2026 | 31 July 2026 | 28 August 2026 |
| August–September 2026 | 30 September 2026 | 28 October 2026 |
| October–November 2026 | 30 November 2026 | 15 January 2027 (exception date) |
| December 2026–January 2027 | 31 January 2027 | 1 March 2027 (28 Feb falls on a Sunday) |
| February–March 2027 | 31 March 2027 | 7 May 2027 (exception date) |
Cycle B — periods ending on even months (April, June, August, October, December, February):
| Taxable period | Period ends | Return & payment due |
| March–April 2026 | 30 April 2026 | 28 May 2026 |
| May–June 2026 | 30 June 2026 | 28 July 2026 |
| July–August 2026 | 31 August 2026 | 28 September 2026 |
| September–October 2026 | 31 October 2026 | 30 November 2026 (28 Nov falls on a Saturday) |
| November–December 2026 | 31 December 2026 | 28 January 2027 |
| January–February 2027 | 28 February 2027 | 29 March 2027 (28 Mar falls on a Sunday) |
Not sure which cycle you are on? Check your most recent GST return confirmation in myIR, or your original GST registration confirmation letter — it will show your assigned taxable periods.
Monthly GST Due Dates 2026/27
Monthly filing is mandatory for businesses with turnover over $24 million, and optional for smaller businesses — commonly chosen by exporters or startups that regularly receive GST refunds and want faster cashflow. Not sure if you even need to be GST-registered yet? See IRD’s GST registration threshold guidance ($60,000/year).
| Period ends | Return & payment due |
| 30 April 2026 | 28 May 2026 |
| 31 May 2026 | 29 June 2026 (weekend adjustment) |
| 30 June 2026 | 28 July 2026 |
| 31 July 2026 | 28 August 2026 |
| 31 August 2026 | 28 September 2026 |
| 30 September 2026 | 28 October 2026 |
| 31 October 2026 | 30 November 2026 (weekend adjustment) |
| 30 November 2026 | 15 January 2027 (exception date) |
| 31 December 2026 | 28 January 2027 |
| 31 January 2027 | 1 March 2027 (weekend adjustment) |
| 28 February 2027 | 29 March 2027 (weekend adjustment) |
| 31 March 2027 | 7 May 2027 (exception date) |
Six-Monthly GST Due Dates 2026/27
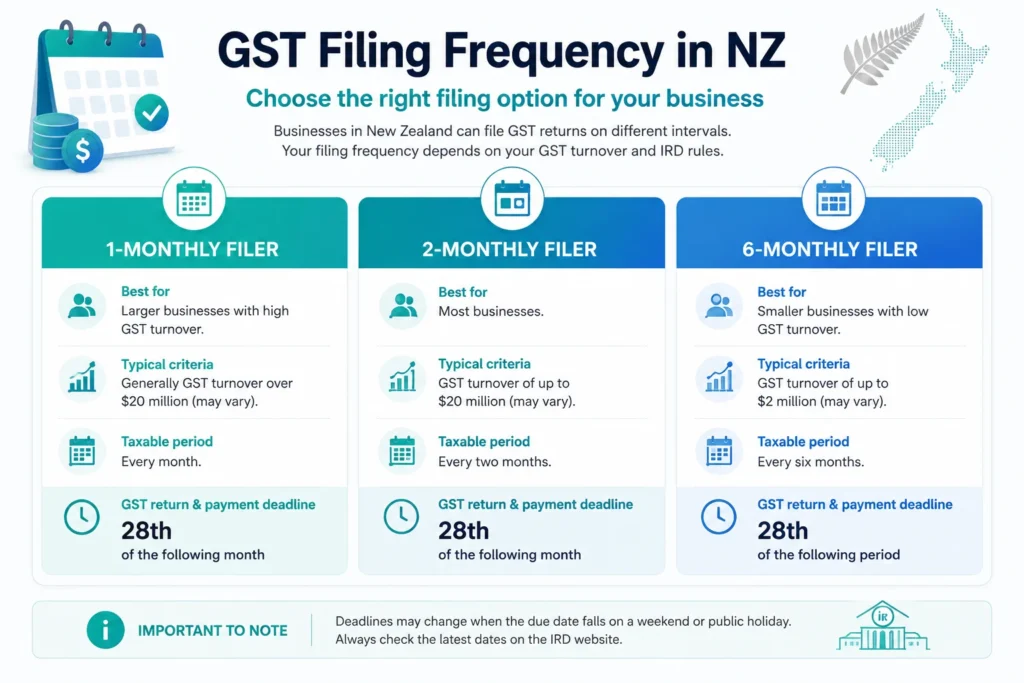
Six-monthly filing is available to businesses with turnover under $500,000/year, giving just two returns per year — the lowest compliance burden, at the cost of holding collected GST funds longer between filings.
| Taxable period | Period ends | Return & payment due |
| April–September 2026 | 30 September 2026 | 28 October 2026 |
| October 2026–March 2027 | 31 March 2027 | 7 May 2027 (exception date) |
Which GST Filing Frequency Should You Choose?
| Frequency | Best suited for | Trade-off |
| Six-monthly | Very small businesses, low transaction volume, steady cashflow | Only 2 returns/year, but you hold collected GST longer |
| Two-monthly (default) | Most small-to-medium businesses | Balanced — manageable filing load, GST not held too long |
| Monthly | Regular GST refund recipients (exporters, high input-cost startups) | More filing admin, but faster refund cashflow |
( Inland Revenue, sections 15 and 15B, Goods and Services Tax Act 1985 — filing frequency eligibility rules.)
What Happens If You File or Pay GST Late?
Inland Revenue applies escalating penalties and interest for late GST filing and payment under the Tax Administration Act 1994, detailed on IRD’s own penalties and interest page:
| Consequence | Amount/rate |
| Late filing penalty | Up to $250 (often reduced for first-time or minor delays) |
| Initial late payment penalty | 1% of unpaid GST, applied the day after the due date |
| Further late payment penalty | An additional 4% if still unpaid 7 days later |
| Use of money interest | Charged monthly on the outstanding balance, at IRD’s set rate |
| Repeated late filing | Can trigger an IRD compliance review or a forced move to monthly filing |
If you can’t pay on time: contacting IRD before the due date to arrange an instalment plan can generally help you avoid the initial late payment penalty — waiting until after the deadline removes that option.
More Free NZ Tax & Payroll Calculators
Managing GST is usually just one piece of a wider tax picture. Explore the rest of our free calculator suite:
Student Loan Calculator — repayments and payoff timeline
GST Calculator — add or remove 15% GST, plus a multi-item invoice builder
PAYE Calculator — full take-home pay breakdown for employees and sole traders paying themselves a salary
Tax Refund Calculator — check whether you’re due a refund alongside your GST obligations
KiwiSaver Calculator — project your balance and government contribution
Frequently Asked Questions
When is my GST return due in New Zealand?
Generally the 28th of the month after your taxable period ends, except for the period ending 30 November – due 15 January and the period ending 31 March – due 7 May.
Can I change my GST filing frequency?
Yes, through myIR or by contacting IRD directly. The change typically takes effect from the start of your next taxable period, provided you still meet the turnover eligibility for the frequency you’re switching to.
What happens if the 28th falls on a weekend or public holiday?
The GST due dates will shift automatically to the next working day. In 2026-27 this affects several deadlines — including 28 June 2026 and 28 February 2027, both of which fall on a Sunday.
Can I file my GST return early?
Yes. You can file and pay any time before the due date, and many businesses do so immediately after their taxable period ends for bookkeeping discipline.
How do I actually file a GST return?
Through myIR, Inland Revenue’s online portal, or via accounting software (Xero, MYOB, QuickBooks, and others) that integrates directly with IRD’s filing system. Need to know the exact amount first? Our GST Calculator handles that in seconds.
What’s the difference between two-monthly Cycle A and Cycle B?
Both are two-monthly filing, just offset by one month — Cycle A periods end on odd months (May, July, September…), while Cycle B periods end on even months (April, June, August…). Your assigned cycle depends on your GST registration date.
How to calculate 15% GST in New Zealand?
To add 15% GST to a GST-exclusive price, multiply the amount by 0.15, then add the GST to the original price. New Zealand’s standard GST rate is 15%.
Formula:
GST = Price × 15%
GST-inclusive price = Price × 1.15
Example:
If the price is $100:
GST = $100 × 15% = $15
Total including GST = $100 + $15 = $115
If your price already includes GST, use 3 ÷ 23 to find the GST component. For example, $115 × 3 ÷ 23 = $15 GST.