KiwiSaver First Home Withdrawal: Complete Guide 2026
If you’ve been a KiwiSaver member for at least 3 years and have never owned a home, you can withdraw most of your KiwiSaver balance — including your own contributions, your employer’s contributions, investment returns, and government contributions — to help buy your first home. You must leave a minimum of $1,000 in your account.
Want to see your projected KiwiSaver balance before you apply? Use our free KiwiSaver Calculator to estimate what you’ll have available.
KiwiSaver First Home Withdrawal Eligibility
To qualify for a first home withdrawal, you must meet all of the following, per Inland Revenue’s official criteria:
| Requirement | Detail |
| Membership length | At least 3 years as a KiwiSaver member (clock starts from your enrolment date, not your first contribution) |
| Home ownership history | Must never have owned a home or land before, in NZ or overseas (with limited exceptions — see below) |
| Property use | Must be your primary residence — cannot be used for an investment property |
| Minimum balance | At least $1,000 must remain in your account after withdrawal |
| Provider type | Applies to KiwiSaver schemes, complying funds, and exempt employer schemes (though not all complying funds permit this — check with your provider’s trustees) |
How Much Can You Withdraw for a First Home?
Eligible members can withdraw almost their entire KiwiSaver balance, including:
- Your own contributions
- Your employer’s contributions
- Investment returns/growth
- Government contributions (member tax credits)
What you cannot withdraw:
- The $1,000 minimum balance, which must stay in your account
- Any funds transferred from an Australian complying superannuation scheme
- Government contributions received during any period you lived overseas without being a NZ permanent resident — Inland Revenue will claw these back if incorrectly withdrawn
Inland Revenue and ANZ KiwiSaver first home withdrawal guidance.)
There is no maximum withdrawal cap — if your balance is $150,000, you can withdraw $149,000, provided you meet all eligibility criteria.
The “Second-Chance” Withdrawal — For Previous Homeowners
If you’ve previously owned a home but are now in a financial position similar to a first-time buyer, you may still qualify — this is informally known as the second-chance withdrawal, assessed by Kāinga Ora, not your KiwiSaver provider.
Common situations where this applies:
- Went through a relationship separation and lost your share of equity in the family home
- Experienced significant financial hardship (e.g., bankruptcy, business failure) and lost property as a result
- Owned property overseas, returned to New Zealand, and have since depleted that asset
The test isn’t simply “have you owned property before” — it’s whether your current financial position is genuinely comparable to someone who has never owned.
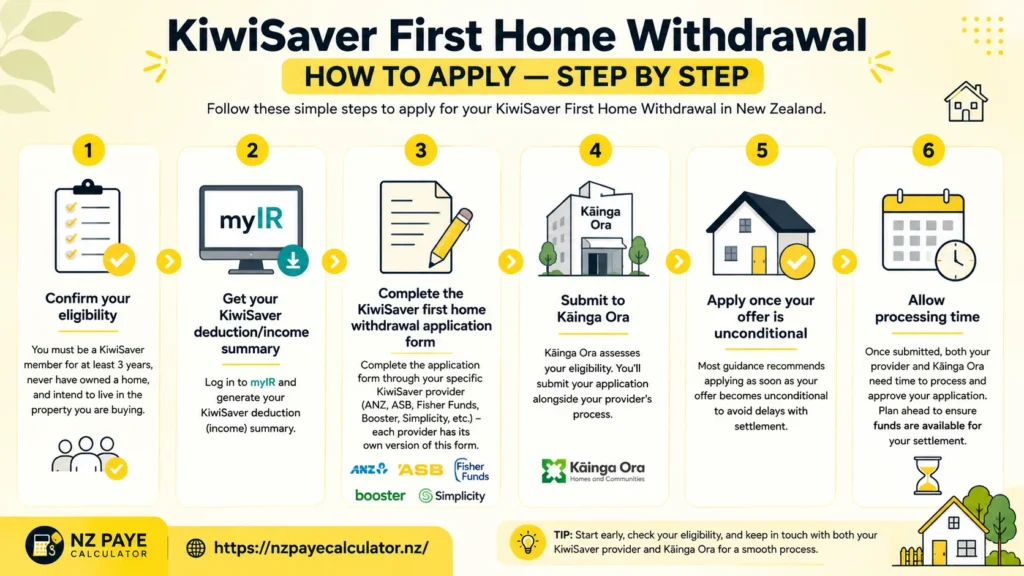
How to Apply — Step by Step
- Confirm your eligibility (3-year membership, never owned a home, intending to live in the property).
- Get your KiwiSaver deduction/income summary — you can generate this directly through myIR.
- Complete the KiwiSaver first home withdrawal application form through your specific KiwiSaver provider (each provider — ANZ, ASB, Fisher Funds, Booster, Simplicity, etc. — has its own version of this form).
- Submit to Kāinga Ora (who assesses eligibility) alongside your provider’s process.
- Apply once your offer is unconditional — most guidance recommends applying as soon as this happens to avoid delays.
- Allow processing time — see timelines below.
How Long Does a KiwiSaver First Home Withdrawal Take?
| Step | Typical timeframe |
| Kāinga Ora eligibility assessment | Generally within 10 working days of receiving a complete application |
| Provider processing after approval | Varies by provider, often an additional few working days |
| Total realistic timeframe | Commonly cited as 10–15 working days end-to-end |
Applying with an incomplete form or missing supporting documents is the most common cause of delay — double-check your provider’s specific document checklist before submitting.
KiwiSaver First Home Withdrawal Form — NZ 2026
If you’re buying your first home in New Zealand, you may be able to withdraw most of your KiwiSaver savings after at least 3 years of membership, provided you meet the eligibility requirements and leave at least $1,000 in your KiwiSaver account. For a first-home withdrawal, you should contact your KiwiSaver provider for its application form and process; you can also use myIR to generate proof of your income and KiwiSaver deductions to support your application.
Download official KiwiSaver withdrawal form:
Important: There isn’t one universal first-home withdrawal form used by every KiwiSaver member. Your KiwiSaver provider normally supplies the application form, so check its current requirements before submitting your application.
2026 KiwiSaver First-Home Withdrawal Figures — Real Market Data
KiwiSaver first-home withdrawals have remained a major and growing source of housing deposit funds through 2026, according to Inland Revenue figures reported via Interest.co.nz:
| Month (2026) | Total early withdrawals | First home share | Hardship share |
| April | $229.6 million (8,620 withdrawals) | $191.1 million (4,220 withdrawals) | $38.5 million (4,410 withdrawals) |
| May | ~$243 million | Majority (first home) | — |
| June | $244.3 million | $200.9 million | $43.4 million |
Key takeaway: first-home withdrawals consistently account for roughly 80–85% of total early withdrawal value each month, confirming this is by far the dominant reason Kiwis access their KiwiSaver early — well ahead of hardship withdrawals. Hardship withdrawals, while smaller in dollar terms, were up 26% by number and 19% by value year-on-year, averaging around $8,700 per person.
(Inland Revenue data as reported by Interest.co.nz, April–June 2026.)
What You Can’t Use a First Home Withdrawal For
- Purchasing an investment property (must be your primary residence)
- A home you’ve already owned before (except under second-chance criteria above)
- Land purchases without an intention to build and live there (Māori land is a specific exception, provided you can demonstrate the right to live on it)
Worked Example
Harry and Emily have each been KiwiSaver members for 5 years. Between their contributions, employer contributions (subject to Employer Superannuation Contribution Tax at 30% on the employer portion), government contributions, and investment growth, they’ve each built a meaningful balance. After leaving the required $1,000 minimum in each account, they combine their withdrawals as a deposit — alongside potentially qualifying for the Kāinga Ora First Home Grant, subject to its own separate eligibility criteria.
Check your own projected numbers first using our KiwiSaver Calculator — enter your income, contribution rate, and years as a member to see a realistic balance estimate before you start the formal application.
Frequently Asked Questions
How much of my KiwiSaver can I withdraw for a first home?
Almost all of it — your own contributions, employer contributions, investment returns, and government contributions — provided you leave a minimum of $1,000 in your account. There’s no maximum withdrawal cap.
Can I withdraw my government contributions for a first home?
Yes, government contributions (member tax credits) can generally be withdrawn for a first home purchase, except for any contributions received during a period you lived overseas without NZ permanent residence — IRD will reclaim those specifically.
How long do I need to be a KiwiSaver member before I can withdraw for a first home?
At least 3 years, counted from your enrolment date — not from when your first contribution actually landed in your account.
Can I make a first home withdrawal if I’ve owned property before?
Generally no, unless you qualify for the “second-chance” withdrawal — assessed by Kāinga Ora — which applies if your current financial position is genuinely comparable to a first-time buyer’s, such as after a relationship separation or financial hardship that resulted in losing a previous property.
How long does a KiwiSaver first home withdrawal take to process?
Commonly 10–15 working days in total, including Kāinga Ora’s eligibility assessment (typically within 10 working days) and your provider’s processing time.
Do I need to use the whole withdrawal at once?
You can generally apply the funds toward your deposit or at settlement, depending on your provider’s process — check the specific timing options with your KiwiSaver provider.
Is there a minimum KiwiSaver balance requirement to apply?
Not a minimum to apply, but you must leave at least $1,000 in your account after the withdrawal is processed.